Saving for retirement can feel like learning a completely new language. 401(k), IRA, Roth, traditional, employer match, contribution limits—it’s easy to wonder where you’re even supposed to start.
The difference between a 401(k) and an IRA becomes much easier to understand once you know how each account works. Both are designed to help you build retirement savings with tax advantages, but they differ in who offers them, how much you can contribute, investment choices, employer contributions, and withdrawal rules.
So when you’re deciding between 401(k) vs IRA, the answer isn’t always “pick one.” In many situations, using both can make sense.
Let’s break down the differences in plain English and look at when an IRA or 401(k) may make more sense.
401(k) vs IRA: The Quick Comparison
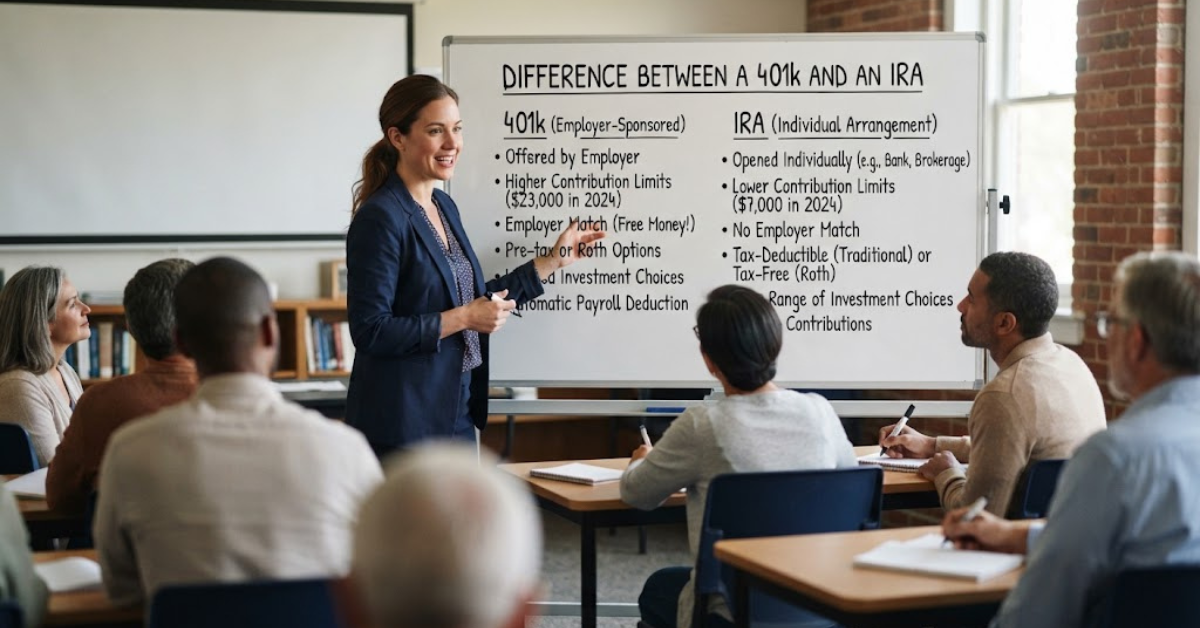
A 401(k) is generally an employer-sponsored retirement plan, while an IRA, or Individual Retirement Arrangement, is an account you open yourself.
Here’s the basic comparison:
| Feature | 401(k) | IRA |
|---|---|---|
| Who opens it? | Usually an employer | Individual |
| Main contribution source | Employee payroll contributions | Individual contributions |
| Employer match | May be available | No employer match |
| 2026 employee contribution limit | $24,500 | $7,500 combined across traditional and Roth IRAs |
| 50+ catch-up | Generally $8,000 | $1,100 |
| Investment choices | Selected by the plan | Usually broader |
| Traditional option | Yes | Yes |
| Roth option | May be available | Yes |
| Tax deduction | Traditional contributions generally pre-tax | Traditional IRA may be deductible, depending on circumstances |
| Income restrictions | Generally no income limit for making regular 401(k) contributions | Roth IRA has income eligibility rules |
| Loans | Some 401(k) plans permit them | Generally no |
| Employer contributions | Possible | No |
For 2026, the IRS says employees can generally contribute up to $24,500 to a 401(k), while the combined annual limit for traditional and Roth IRAs is $7,500. The 2026 catch-up limit is generally $8,000 for 401(k) participants age 50 or older and $1,100 for IRA owners age 50 or older.
Those numbers alone explain why the two accounts can play very different roles in a retirement strategy.
What Is a 401(k)?
A 401(k) is a retirement plan offered through an employer.
Instead of opening the account yourself at a brokerage, you typically enroll through your workplace. You then choose how much of each paycheck to contribute, subject to the plan’s rules and federal limits.
With a traditional 401(k), employee contributions are generally made through payroll before federal income taxes are applied. Employers may also contribute to the account through matching or other contributions.
For many employees, that employer contribution is one of the biggest advantages of a 401(k).
How Does an Employer Match Work?
Suppose your employer says it will match a percentage of your contributions.
You contribute part of your paycheck, and the employer adds money according to the plan’s matching formula.
That employer contribution can significantly increase the amount going toward retirement.
The IRS specifically warns that failing to contribute enough to receive an available employer match can mean leaving potential retirement money on the table.
However, employer contributions may be subject to vesting rules. That means you may have to work for the company for a certain period before you fully own some or all of the employer contributions.
What Is an IRA?
IRA stands for Individual Retirement Arrangement.
Unlike a 401(k), an IRA isn’t normally tied to your employer. You can generally open one through a brokerage, bank, or other financial institution that offers IRAs.
The two main types most people encounter are:
- Traditional IRA
- Roth IRA
Both provide tax advantages, but they work differently.
The biggest attraction of an IRA is often control. Rather than being limited to the investment menu selected by your employer’s retirement plan, you may have access to a much broader range of investments depending on the financial institution.
What Is the Difference Between an IRA and a 401(k)?
The difference between an IRA and a 401(k) starts with who controls the account.
A 401(k) is connected to your employer. The employer chooses the plan provider and establishes the plan’s investment options and rules.
An IRA belongs to you individually.
That means you don’t need to wait for an employer to offer one. You can generally open an IRA yourself if you meet the applicable requirements.
The contribution limits are also dramatically different.
In 2026, the employee contribution limit for most 401(k) plans is $24,500, while the combined contribution limit for your traditional and Roth IRAs is $7,500.
401(k) vs IRA: Contribution Limits
This is one of the biggest practical differences.
401(k) Contribution Limit
For 2026, the employee elective deferral limit for most 401(k) plans is $24,500.
Workers age 50 and older can generally make an additional $8,000 catch-up contribution, bringing the total to $32,500.
There is also a special higher catch-up limit for employees ages 60 through 63. For 2026, that higher catch-up amount is $11,250.
Keep in mind that the overall 401(k) plan contribution limit is different from the employee salary-deferral limit because employer contributions can also count toward the overall limit.
IRA Contribution Limit
For 2026, the combined contribution limit for traditional and Roth IRAs is $7,500.
If you’re age 50 or older, the catch-up contribution is $1,100, making the total $8,600.
Importantly, that $7,500 is a combined limit.
You can’t contribute $7,500 to a traditional IRA and another $7,500 to a Roth IRA simply because you have two different accounts.
Traditional 401(k) vs Traditional IRA
The comparison becomes more interesting when you look at the traditional versions.
Both can offer tax benefits today in exchange for generally taxable withdrawals later.
Traditional 401(k)
Money is generally contributed through payroll on a pre-tax basis.
That can reduce your taxable income for the year of the contribution.
The money can then grow inside the retirement account without being taxed annually as ordinary investment income.
Generally, withdrawals from a traditional 401(k) are taxable.
Traditional IRA
Traditional IRA contributions may be deductible, but the deduction isn’t automatically available to everyone.
Your eligibility can depend on factors such as your income, filing status, and whether you or your spouse is covered by a workplace retirement plan.
For 2026, the IRS has specific income phase-out ranges for the deduction when a taxpayer is covered by a workplace retirement plan.
That’s an important distinction.
You can generally contribute to a traditional IRA even when you can’t deduct the entire contribution.
Roth 401(k) vs Roth IRA
Now we get to the other side of the tax equation.
With Roth accounts, contributions are generally made with after-tax money.
You don’t get the same upfront tax deduction that traditional contributions may provide.
In exchange, qualified Roth distributions can generally be tax-free.
Roth 401(k)
A workplace plan may offer a designated Roth 401(k) option.
You contribute after-tax money through payroll, and qualified distributions can receive Roth tax treatment.
Not every employer offers a Roth option, so you’ll need to check your plan.
Roth IRA
A Roth IRA is opened individually.
Contributions aren’t deductible, but qualified distributions can be tax-free.
Unlike a traditional IRA, the original owner of a Roth IRA doesn’t have to take required minimum distributions during their lifetime under current federal rules.
Roth IRA eligibility can also be affected by income.
That makes the Roth IRA different from a Roth 401(k), where the ability to make employee contributions generally isn’t subject to the same Roth IRA income limits.
401(k) vs IRA: Which Has Better Investment Choices?
This depends heavily on the specific 401(k) plan.
An employer’s 401(k) usually offers a curated menu of investments. That may include:
- Mutual funds
- Target-date funds
- Index funds
- Stable-value funds
- Other plan-specific investments
The advantage is simplicity.
The downside is that you can’t usually choose from the entire investment universe.
An IRA often provides considerably more investment flexibility, depending on the provider.
You may be able to choose among:
- Stocks
- Bonds
- Mutual funds
- ETFs
- Index funds
- Target-date funds
- Other eligible investments
So if your employer’s 401(k) has expensive or limited investment choices, an IRA can sometimes provide more flexibility.
But don’t assume every IRA is automatically better. Fees, available investments, customer service, and account features all matter.
IRA or 401(k): Which Should You Choose First?
For many employees, there’s a straightforward starting point:
Look at the employer match first.
If your employer offers matching contributions, contributing enough to receive the full match can be an attractive priority because you’re potentially receiving additional employer money.
After that, the decision becomes more personal.
A common approach may look like this:
- Contribute enough to the 401(k) to receive the full employer match.
- Consider contributing to a Roth or traditional IRA, depending on your tax situation and eligibility.
- If you still have retirement money available to invest, consider increasing your 401(k) contributions.
- Continue building an appropriate emergency fund and managing high-interest debt alongside retirement savings.
This isn’t a universal formula, but it illustrates why the answer to “IRA or 401(k)?” doesn’t have to be one or the other.
Can You Have Both a 401(k) and an IRA?
Yes.
Having both is completely possible.
In fact, many people use both accounts because they offer different advantages.
For example, you might contribute enough to your workplace 401(k) to capture the employer match and then contribute to an IRA for additional investment flexibility.
You can also continue contributing to your 401(k), subject to its limits, while contributing to an IRA, subject to IRA rules.
The contribution limits are separate, although there are important tax-deduction and eligibility rules to understand.
401(k) vs IRA: Early Withdrawals
Retirement accounts are designed primarily for long-term saving, so taking money out early can result in taxes and penalties depending on the account and circumstances.
Traditional 401(k) and traditional IRA withdrawals are generally taxable, and an additional 10% tax can apply to certain early distributions unless an exception applies.
Roth accounts have their own rules.
For a Roth IRA, for example, your contributions are treated differently from investment earnings, and qualified distributions of earnings can be tax-free.
Because exceptions can be complicated, don’t assume that every early withdrawal will automatically receive the same tax treatment.
Can You Borrow From a 401(k)?
Some 401(k) plans allow participants to take loans from their accounts.
But this is a plan feature, not a universal 401(k) right.
The rules, limits, repayment requirements, and consequences of leaving your employer can vary.
IRAs generally don’t offer 401(k)-style participant loans.
That doesn’t mean an IRA is inaccessible before retirement under every circumstance. Certain withdrawals can qualify for specific exceptions, but the rules are different from a 401(k) loan.
401(k) vs IRA: Required Minimum Distributions
Required minimum distributions, commonly called RMDs, are another important difference to understand.
Under current federal rules, traditional IRAs and most traditional workplace retirement plans generally require RMDs beginning at age 73.
There is an important distinction for some workplace plans: an employee who continues working may generally be able to delay RMDs from their current employer’s plan until retirement, unless they are a 5% owner of the business.
Roth IRAs don’t require RMDs during the original owner’s lifetime.
Designated Roth accounts in a 401(k) also aren’t subject to lifetime RMDs for the original owner under current rules.
These rules can be particularly important for retirement and estate planning.
What Happens to Your 401(k) When You Change Jobs?
Your 401(k) doesn’t necessarily disappear when you leave an employer.
Depending on the circumstances and plan rules, you may have several options, including:
- Leaving the money in the old employer’s plan
- Rolling it into a new employer’s retirement plan, if permitted
- Rolling it into an IRA
- Taking a taxable distribution
A rollover can allow retirement money to remain tax-advantaged, but the details matter.
A direct rollover is generally different from simply receiving the money yourself and depositing it later.
If you’re changing jobs, understand the tax consequences before moving retirement funds.
401(k) vs IRA Fees
Fees deserve more attention than they usually get.
A difference of even a fraction of a percentage point in annual investment expenses can become meaningful over several decades because you’re not only losing the fee itself—you may also lose the investment growth that money could have generated.
When comparing accounts, look at:
- Investment expense ratios
- Administrative fees
- Advisory fees
- Trading costs
- Account maintenance fees
- Fund selection
- Other plan-specific charges
A 401(k) isn’t automatically expensive, and an IRA isn’t automatically cheap.
Compare the actual numbers.
401(k) vs IRA: Pros and Cons
401(k) advantages
- Higher annual employee contribution limit
- Potential employer matching
- Convenient payroll contributions
- Traditional and sometimes Roth options
- Potential access to plan loans
- Useful for building substantial retirement savings
401(k) disadvantages
- Investment choices may be limited
- Fees vary by employer plan
- You generally need an eligible employer plan
- Some employer contributions may have vesting requirements
- Plan rules can be complicated
IRA advantages
- Easy to open independently
- Usually broad investment choices
- Traditional and Roth options
- Greater personal control
- Useful for retirement diversification
- Can complement an employer retirement plan
IRA disadvantages
- Much lower annual contribution limit
- Traditional IRA deductions can be limited by income and workplace coverage
- Roth IRA contributions have income eligibility rules
- No employer matching
- Generally no participant loans
So, 401(k) or IRA?
If you’re still wondering “IRA or 401(k)?”, start by asking a few practical questions.
Does your employer offer a match?
If yes, investigate how much you need to contribute to receive the full match.
Does your 401(k) have good investment options?
Look at the funds, expenses, and available choices.
Are you eligible for a Roth IRA?
Your income and tax-filing situation can affect eligibility.
What’s your current tax situation?
Traditional contributions may provide a tax benefit today, while Roth contributions generally trade that immediate deduction for potentially tax-free qualified withdrawals later.
How much can you afford to save?
The best retirement account is not much use if the contribution amount isn’t sustainable.
Your savings rate matters enormously.
A Simple Example
Imagine an employee earns $70,000 a year.
Their employer offers a 401(k) with a match and the employee has access to an IRA.
Instead of thinking:
“Should I choose the 401(k) or the IRA?”
they might think:
“How can I use each account for its strongest advantage?”
They could contribute enough to the 401(k) to qualify for the full employer match.
Then they could consider contributing to an IRA for greater investment flexibility.
If they still have money available for retirement, they could increase their 401(k) contributions.
The exact strategy depends on income, taxes, employer benefits, investment costs, and personal goals.
Frequently Asked Questions
What is the difference between a 401(k) and an IRA?
The biggest difference is that a 401(k) is generally an employer-sponsored retirement plan, while an IRA is an individual retirement account you open yourself. A 401(k) generally has a much higher contribution limit and may offer an employer match.
Is a 401(k) better than an IRA?
Not necessarily. A 401(k) can be particularly valuable when your employer offers matching contributions and when you want to save more than the IRA contribution limit allows. An IRA may offer greater investment flexibility.
Can I have a 401(k) and an IRA at the same time?
Yes. You can generally contribute to both, provided you follow the applicable contribution, income, deduction, and eligibility rules.
What is the 401(k) contribution limit for 2026?
For 2026, the employee elective deferral limit for most 401(k) plans is $24,500. The general catch-up contribution for employees age 50 or older is $8,000, with a higher catch-up limit applying to certain employees ages 60 through 63.
What is the IRA contribution limit for 2026?
The combined contribution limit for traditional and Roth IRAs is $7,500 in 2026, or $8,600 for people age 50 or older.
Is a Roth IRA better than a Roth 401(k)?
Neither is automatically better. A Roth 401(k) can offer a much higher contribution limit, while a Roth IRA can provide broader investment choices and has no lifetime RMD requirement for the original owner under current rules.
Does an IRA have an employer match?
No. An IRA is an individual account, so it doesn’t receive an employer match. Employer matching is a feature associated with certain workplace retirement plans.
Can I contribute to a traditional IRA if I have a 401(k)?
Yes. Having a 401(k) doesn’t automatically prevent you from contributing to a traditional IRA. However, whether you can deduct that IRA contribution may depend on your income, filing status, and workplace retirement-plan coverage.
Should I max out my 401(k) or IRA first?
There’s no universal answer. If your employer offers a match, getting the full match is often an important first consideration. After that, an IRA can offer additional investment flexibility, while the 401(k) provides a substantially higher contribution ceiling.
Is a 401(k) an IRA?
No. They’re separate types of retirement accounts. A 401(k) is generally an employer-sponsored retirement plan, while an IRA is an individual retirement arrangement.
Final Takeaway: 401(k) vs IRA
The difference between a 401(k) and an IRA comes down to more than contribution limits.
A 401(k) gives you the major advantage of higher contribution limits and potential employer matching. An IRA gives you individual ownership and often greater investment flexibility.
For 2026, the difference in contribution capacity is substantial: most employees can put up to $24,500 of their own salary into a 401(k), compared with a combined $7,500 across traditional and Roth IRAs.
That’s why the 401(k) vs IRA decision doesn’t always have to be a competition.
For many people, the better question is how the two accounts can work together.
If you’re deciding between an IRA or 401(k), start by checking your employer’s matching policy, reviewing the fees and investment choices in your 401(k), and understanding how traditional and Roth tax treatment fits your situation. Then consider how much you can realistically save each month.
Retirement planning isn’t about finding one magical account. It’s about choosing the right tools and consistently putting them to work.