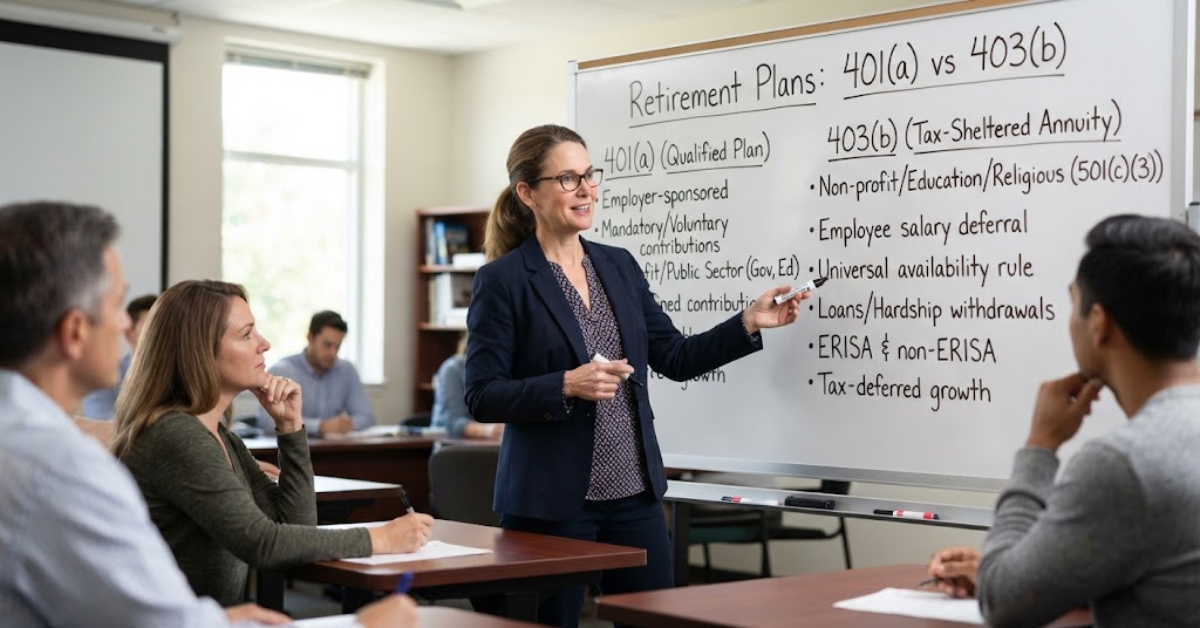
Retirement plans can look like a bowl of alphabet soup: 401(a), 401(k), 403(a), 403(b), 457(b)—and they can all sound almost identical at first.
But the difference between 401a and 403b is important if your employer offers one of these plans. They have different eligibility rules, plan structures, contribution features, and investment arrangements.
In simple terms, a 401(a) plan is a qualified retirement plan governed by Section 401(a) of the Internal Revenue Code, while a 403(b) is a tax-sheltered retirement plan primarily available to employees of public schools and certain tax-exempt organizations.
So, what is a 401a plan, how does it compare with a 403(b), and what does 403a vs 403b actually mean?
Let’s break it down.
What Is a 401(a) Plan?
A 401(a) plan is a qualified employer-sponsored retirement plan that meets the requirements established under Section 401(a) of the Internal Revenue Code.
The term can be confusing because 401(a) isn’t one single standardized retirement product in the same way people often think of a 401(k). Instead, Section 401(a) establishes requirements that qualified retirement plans must meet to receive favorable tax treatment.
A 401(a) plan can be structured as a defined contribution plan or, depending on its design, another type of qualified retirement arrangement.
These plans are particularly common among governmental employers, public-sector organizations, universities, and other employers using qualified retirement arrangements. The IRS notes that public employers may establish 401(a) plans, and governmental 401(a) plans can cover employees of federal, state, local, and tribal governmental entities.
How Does a 401(a) Work?
The exact rules depend heavily on the plan document.
For example, a 401(a) plan may require employees to contribute a specific percentage of their salary. In other arrangements, the employer may make contributions on behalf of employees.
The important point is that the employer generally has more control over how the plan is structured than employees might expect.
A 401(a) plan can specify things such as:
- Who is eligible
- Required or optional employee contributions
- Employer contribution formulas
- Vesting requirements
- Investment choices
- Distribution rules
- Withdrawal provisions
The IRS explains that Section 401(a) establishes requirements covering eligibility, vesting, contributions, and distributions for qualified plans.
What Is a 403(b) Plan?
A 403(b) plan, sometimes called a tax-sheltered annuity (TSA) plan, is designed primarily for employees of public schools and certain tax-exempt organizations.
Eligible employers can include:
- Public schools
- Public colleges and universities
- Certain 501(c)(3) organizations
- Certain churches and church-related organizations
- Certain eligible ministers
The IRS describes a 403(b) as a retirement plan in which employees can contribute part of their salary to individual retirement accounts, while employers may also contribute.
A traditional 403(b) contribution is generally made before federal income tax, allowing taxes on the contribution and investment earnings to be deferred until money is withdrawn. A 403(b) may also offer a Roth option, in which contributions are taxed up front and qualified withdrawals can be tax-free.
Difference Between 401a and 403b at a Glance
Here’s the easiest way to compare the two:
| Feature | 401(a) | 403(b) |
|---|---|---|
| Main purpose | Qualified employer retirement plan | Tax-sheltered retirement plan |
| Common employers | Government and other qualified-plan sponsors | Public schools and certain nonprofits |
| Employee contributions | Depends on plan design | Commonly through salary deferrals |
| Employer contributions | Often an important part of the plan | May be offered |
| Roth option | Depends on plan design | May be available |
| Investment options | Depends on plan | Annuities and custodial mutual-fund accounts are common |
| Contribution rules | Depend on plan and applicable IRS limits | Subject to 403(b) limits and special rules |
| Plan structure | Highly dependent on employer plan | Governed specifically by Section 403(b) |
| Employee control | Often more limited by plan design | Employees commonly choose salary-deferral amounts |
The biggest takeaway is this: a 401(a) is primarily defined by the qualified-plan rules under Section 401(a), while a 403(b) is a specific type of tax-sheltered retirement arrangement for eligible organizations.
401(a) vs 403(b): Who Can Participate?
Eligibility is one of the biggest differences.
A 403(b) is restricted to specific categories of employers. The IRS specifically identifies public schools and qualifying 501(c)(3) organizations among the employers that can establish 403(b) plans.
A 401(a) can be used in a broader range of qualified-plan arrangements, including governmental plans.
For governmental 401(a) plans, eligible employers can include:
- The federal government and its agencies
- States
- Political subdivisions
- Governmental agencies or instrumentalities
- Certain tribal governments
The exact eligibility requirements still depend on the plan and applicable law.
This means you generally don’t choose between a 401(a) and 403(b) simply because you prefer one. Your employer’s eligibility and plan design largely determine which retirement plan is available to you.
Employee Contributions: 401(a) vs 403(b)
Another major difference is how employees contribute.
With a 403(b), employee salary deferrals are a central feature. You typically elect to have part of your paycheck contributed to the plan.
For 2026, the basic 403(b) elective-deferral limit is $24,500. Employees age 50 and older may generally have an additional $8,000 catch-up contribution, while people who turn 60, 61, 62, or 63 during the year may qualify for the higher $11,250 catch-up limit under the applicable rules.
Some eligible 403(b) participants can also qualify for a special 15-years-of-service catch-up provision, if their plan permits it.
401(a) plans are different because the plan document determines how employee and employer contributions are structured.
Some 401(a) arrangements require employee contributions. Others may primarily or entirely rely on employer contributions.
That’s why two people can both have “401(a)” plans but have noticeably different contribution rules.
Employer Contributions Can Be a Big Deal
If you’re comparing a 401(a) and 403(b) offered by an employer, don’t focus only on the employee contribution limit.
Look closely at the employer contribution.
A 401(a) plan may include mandatory employer contributions or required employee contributions established by the plan. Governmental 401(a) arrangements can also involve employer “pick-up” contributions under specific tax rules.
A 403(b), meanwhile, can also receive employer contributions, including matching or nonelective contributions, depending on the plan.
The practical question is:
How much money does your employer actually put into the account, and what do you have to contribute to receive it?
That number can matter more than the plan’s name.
Investment Options in 401(a) and 403(b) Plans
Investment choices can vary dramatically from one employer to another.
With a 403(b), the IRS allows individual accounts to be structured using arrangements such as:
- Annuity contracts
- Custodial accounts invested in mutual funds
- Retirement income accounts for certain church employees
The exact investments available depend on the employer’s plan and its providers.
A 401(a) plan also doesn’t have one universal investment menu.
Your employer’s plan might offer mutual funds, target-date funds, stable-value investments, or other permitted investment choices.
So if you’re deciding which plan is better, don’t assume that every 401(a) has better investments than every 403(b), or vice versa.
Compare the actual investment menu and fees.
401(a) vs 403(b): Which Has Better Tax Benefits?
Both types of plans can provide significant tax advantages, but the details depend on the plan.
With a traditional 403(b), eligible contributions are generally excluded or deducted from current taxable income, while investment earnings can grow tax-deferred until distribution. Roth 403(b) contributions work differently because they are taxed when contributed.
Qualified 401(a) plans also receive favorable tax treatment. Employer contributions and investment earnings can generally receive tax-deferred treatment under the applicable rules until distributed.
However, tax treatment isn’t the only thing that matters.
You should also consider:
- Contribution requirements
- Employer contributions
- Vesting schedule
- Investment expenses
- Administrative fees
- Roth availability
- Loan provisions
- Withdrawal rules
- Rollover options
A plan with slightly different tax characteristics could still be more attractive if the employer contribution is substantially better.
403a vs 403b: Are They the Same Thing?
No. This is an easy place to get confused.
When people search for 403a vs 403b, they may actually mean 403(a) vs 403(b).
These are separate provisions of the Internal Revenue Code.
What Is a 403(a) Plan?
A 403(a) plan is generally a qualified annuity plan that meets the requirements of Section 403(a).
It isn’t the same thing as a 403(b) plan.
A 403(b), on the other hand, is specifically a tax-sheltered annuity plan for eligible employees of public schools and certain tax-exempt organizations.
The terminology can be especially confusing because both numbers contain “403,” but the letters matter.
403(a) ≠ 403(b).
And neither should automatically be treated as another name for a 401(a) plan.
401(a) vs 403(b) Contribution Limits
Contribution limits are another area where retirement-plan comparisons can get complicated.
For 2026, the IRS lists the basic elective-deferral limit for 403(b) plans at $24,500. The overall annual-additions limit for a 403(b) is generally the lesser of $72,000 or 100% of includible compensation, subject to the applicable rules.
The important distinction is that the $24,500 figure is the employee elective-deferral limit, not necessarily the maximum amount that can go into the account from every source.
Employer contributions can also count toward applicable overall contribution limits.
For a 401(a) plan, the applicable limits depend on the type and design of the plan and the relevant IRS rules.
So don’t assume that a 401(a) automatically has a $24,500 employee contribution limit simply because 401(a) is related to the broader family of qualified retirement plans.
Vesting: Another Important Difference
Vesting determines how much of an employer contribution you get to keep if you leave your job.
Your own contributions are generally yours, but employer contributions can sometimes be subject to a vesting schedule.
For example, imagine an employer contributes $5,000 to your retirement account each year but requires three years of service for full vesting.
If you leave before satisfying the plan’s vesting requirements, you may not be entitled to keep all of those employer contributions.
This is why you should always check the plan’s vesting schedule, particularly if you’re considering changing jobs.
Can You Have Both a 401(a) and a 403(b)?
In some circumstances, yes.
Whether you can participate in both depends on your employer, the specific plans, and the applicable contribution rules.
This is particularly relevant for employees of public institutions or educational organizations that offer multiple retirement arrangements.
One important point: elective deferral limits can apply across certain plans.
For example, the IRS states that employees who participate in a 403(b) and certain other employer plans generally must aggregate elective deferrals for purposes of the annual elective-deferral limit.
So having access to multiple accounts doesn’t necessarily mean you can contribute the full annual limit separately to each one.
401(a) vs 403(b): Which Is Better?
There isn’t a universal winner.
The better plan is usually the one that gives you the strongest combination of employer contributions, reasonable fees, useful investment choices, and favorable plan rules.
Here’s a practical way to compare them:
Choose Based on These Five Factors
1. Employer contribution
How much does your employer contribute?
2. Vesting
How quickly do employer contributions become fully yours?
3. Investment expenses
Low-cost investment options can make a meaningful difference over a long retirement timeline.
4. Investment selection
Does the plan provide diversified choices that fit your goals?
5. Flexibility
Check whether the plan offers Roth contributions, loans, hardship withdrawals, rollovers, and other features you may value.
The name “401(a)” or “403(b)” tells you what kind of legal framework the plan falls under. It doesn’t automatically tell you which specific plan is better.
What Is a 401a Plan? A Quick Example
Suppose a public university offers employees a 401(a) plan.
The university might establish a formula requiring the employer to contribute a certain percentage of an employee’s compensation. The plan could also require the employee to contribute a specified amount.
Another university might use a different contribution structure.
That’s why the answer to “what is a 401a plan?” can’t be reduced to one contribution formula.
A 401(a) is better understood as a qualified retirement-plan framework governed by Section 401(a), with the specific features determined by the plan document.
Common Mistakes When Comparing 401(a) and 403(b)
A few misconceptions come up repeatedly.
Mistake #1: Assuming 401(a) Means 401(k)
They aren’t the same thing.
A 401(k) is a specific type of qualified defined contribution plan that allows employees to make elective salary deferrals. A 401(a) refers to the broader qualified-plan requirements under Section 401(a).
Mistake #2: Assuming 403(b) Means Annuity Only
The name “tax-sheltered annuity” can be misleading.
A 403(b) can use annuity contracts, but it can also use custodial accounts invested in mutual funds and certain retirement income accounts.
Mistake #3: Looking Only at Contribution Limits
A higher contribution limit doesn’t automatically make a plan better.
Employer contributions, fees, investment options, and vesting can have a much larger practical impact on your retirement savings.
Mistake #4: Assuming All 401(a) Plans Work the Same Way
They don’t.
The specific plan document determines many important features, including contribution requirements and vesting provisions.
How to Compare Your 401(a) and 403(b) Options
If your employer gives you a choice or access to multiple retirement plans, use this checklist:
- Find the summary plan description or plan documents.
- Check your required employee contribution.
- Calculate the employer contribution.
- Review the vesting schedule.
- Compare investment expense ratios.
- Look for administrative or recordkeeping fees.
- Check whether a Roth option is available.
- Review withdrawal and rollover rules.
- Check whether loans are permitted.
- Consider how the plan fits with your other retirement accounts.
Don’t make the decision based solely on the three numbers in the plan’s name.
FAQs About the Difference Between 401a and 403b
Is a 401(a) better than a 403(b)?
Not necessarily. The better option depends on the specific employer contribution, fees, investment choices, vesting rules, and other features of each plan.
What is a 401a plan used for?
A 401(a) plan is used as a qualified employer-sponsored retirement arrangement. It is particularly common in government and public-sector settings, although qualified 401(a) plans can be structured in different ways.
What is the main difference between 401(a) and 403(b)?
The biggest difference is their legal and eligibility framework. A 401(a) is a qualified retirement-plan framework under Section 401(a), while a 403(b) is a specific tax-sheltered retirement plan available to eligible employees of public schools and certain tax-exempt organizations.
Can teachers have a 401(a) and 403(b)?
Potentially, yes. A teacher’s employer may offer more than one retirement arrangement, but eligibility and contribution rules depend on the specific employer and plans.
Is a 403(b) the same as a 401(k)?
No. They have some similarities, but they are governed by different sections of the tax code and are generally offered by different types of employers. The IRS describes a 403(b) as a plan for public schools and certain tax-exempt organizations, while a 401(k) is a type of qualified defined contribution plan commonly used by employers more broadly.
What does 403a vs 403b mean?
403(a) and 403(b) are different retirement-plan categories. A 403(a) generally refers to a qualified annuity plan, while a 403(b) is a tax-sheltered annuity plan for eligible employees of public schools and certain tax-exempt organizations.
What is the 403(b) contribution limit for 2026?
The basic 2026 elective-deferral limit for a 403(b) is $24,500. Additional catch-up contributions may be available depending on age and, in some cases, years of service.
Can a 403(b) have Roth contributions?
Yes. A 403(b) plan may offer a designated Roth account. Roth contributions are included in taxable income when contributed, while qualified Roth distributions can generally be tax-free.
Conclusion: Understanding 401(a) vs 403(b)
The difference between 401a and 403b becomes much easier to understand once you stop looking at the numbers and focus on how each plan works.
A 401(a) is a qualified retirement-plan framework with features determined largely by the employer’s plan design. A 403(b) is a tax-sheltered retirement plan primarily designed for employees of public schools and certain tax-exempt organizations.
The most important comparison isn’t simply 401(a) vs 403(b). Look at the details that affect your money:
- Employer contributions
- Employee contribution requirements
- Vesting
- Investment choices
- Fees
- Roth availability
- Withdrawal rules
- Rollover options
And if you see people searching for 403a vs 403b, remember that the “a” and “b” refer to different sections of the tax code—they aren’t interchangeable terms.
If you’re deciding between retirement options at work, the smartest next step is to compare the actual plan documents and fee information rather than relying on the plan name alone.